A solar quote can look exciting until the financing page appears. The right solar panel financing can make a project manageable and protect your cash flow. The wrong structure can reduce savings, create surprises at sale time, or leave valuable incentives on the table. Before choosing an installer or signing an agreement, compare how each option affects ownership, monthly costs, tax benefits, and your long-term return.
Start With the Project Economics
Financing should support a solar project that makes sense for your property, not force a project into your budget. Begin with your recent electric bills, your expected energy use, available roof or land space, and the condition of the site. A well-sized system is usually more valuable than an oversized one designed only to produce a low-looking payment.
Ask each contractor to show estimated annual production, projected utility savings, installed price, financing assumptions, and any incentives included in the estimate. For businesses, farms, and public entities, request assumptions about demand charges, operating schedules, and applicable depreciation or grant opportunities. A clear proposal makes it easier to compare offers that may use very different payment structures.
Solar savings are not always immediate or identical from one property to the next. Utility rates, local net-metering rules, shading, roof age, and future electricity consumption all matter. Treat savings estimates as planning tools, not guarantees, and make sure the payment fits even if production or utility prices differ from projections.
Solar Panel Financing Options to Compare
Most buyers choose among cash purchases, loans, leases, and power purchase agreements. Commercial and institutional buyers may also use specialized structures. Each route has a legitimate use case, but ownership is the main dividing line.
Cash Purchase
Paying cash generally delivers the strongest long-term return because there is no interest expense or lender fee. The system owner can usually claim available federal, state, or local incentives if eligible, and all electricity savings remain with the property owner.
The trade-off is the upfront investment. A cash purchase may not be the best fit if it would deplete emergency reserves, delay a revenue-producing business improvement, or compete with other essential capital needs. Ask for the cash price separately. It is the baseline for judging every financed offer.
Solar Loans
A solar loan lets you own the system while spreading the cost over time. This can be a practical fit for homeowners who want to preserve cash, as well as businesses and agricultural operators that prefer predictable payments while retaining ownership benefits.
Look beyond the advertised interest rate. Some loans include dealer fees that are built into the project price, while others offer a lower upfront cost but a higher rate. Compare the total amount financed, loan term, monthly payment, origination fees, prepayment terms, and the total cost over the life of the loan.
Also ask whether the quoted payment assumes you will apply a tax credit or incentive toward the balance. That may be reasonable if you expect to qualify, but understand what your payment becomes if you do not make that extra payment. Incentive eligibility depends on your tax situation, project details, and current rules, so confirm it with a qualified tax professional.
Home Equity Financing
A home equity loan or line of credit may offer competitive terms for qualified homeowners because the financing is secured by the home. It can be worth comparing with a dedicated solar loan, particularly when a borrower has substantial equity and plans to stay in the property for several years.
However, the home serves as collateral. Variable-rate lines of credit can also change over time. Consider the risks carefully, and do not select this option solely because the initial payment is low.
Solar Leases and Power Purchase Agreements
With a solar lease, you pay a fixed monthly amount for the use of the equipment. With a power purchase agreement, often called a PPA, you pay for the electricity the system produces at an agreed rate. In both cases, a third party typically owns the system and receives ownership-related incentives.
These arrangements can reduce or eliminate upfront costs and may work for buyers who prioritize predictable expenses over ownership. They are common in some commercial, nonprofit, and public-sector applications as well.
Read the agreement closely. Check the contract length, annual payment escalator, production guarantees, maintenance responsibility, early termination terms, and options if you sell the property. A low first-year payment is not enough information to judge the full value of a lease or PPA.
Commercial, Agricultural, and Public-Sector Structures
Larger projects often require a more tailored approach. Businesses may use equipment financing, operating leases, or third-party ownership arrangements. Farms may coordinate solar investments with seasonal cash flow and energy-intensive operations such as irrigation, refrigeration, or processing. Government agencies, schools, and nonprofits may evaluate PPAs, grants, or other structures designed for tax-exempt entities.
The best choice depends on who can use incentives, how the organization handles capital spending, and whether energy savings need to support a specific operating budget. Work with solar contractors experienced in your property type, then involve your finance and tax advisors before committing.
Compare Total Cost, Not Just the Monthly Payment
A monthly payment is easy to understand, which is why it is often the first number presented. But it does not tell the whole story. A longer term can lower the payment while increasing total interest. A lease can offer convenience but may limit the financial upside that comes with ownership. A loan with a low rate may still have a higher project price because of embedded fees.
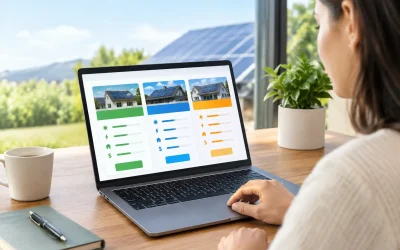
For each proposal, put the following figures side by side: installed system price, upfront payment, loan fees, interest rate, term length, total payments, estimated first-year savings, projected incentive treatment, and system ownership. If a contractor cannot provide these details in plain language, pause before moving forward.
For commercial buyers, include maintenance costs, insurance requirements, accounting treatment, and any expected changes in utility demand charges. For agricultural properties, account for production cycles and whether the system is intended to offset a stable year-round load or a seasonal one.
Questions to Ask Before You Sign
The right questions can reveal whether a financing offer is truly competitive. Ask who owns the system from day one, whether the financing creates a lien, and what happens if you sell or refinance the property. Ask whether there are prepayment penalties and whether the lender pays the installer before final system approval.
You should also confirm who handles permits, interconnection, monitoring, warranty claims, and maintenance. Financing and installation are connected, but they are not the same decision. A strong contractor should explain both without pressure and give you time to review the paperwork.
Be cautious about promises that your utility bill will disappear completely. Most properties still have fixed utility charges, and actual savings depend on local billing rules and system performance. Honest estimates explain those limits upfront.
Make Quotes Compete on Clear Terms
Request at least two or three detailed quotes from qualified solar professionals. Give each contractor the same information about your electricity use and goals so the proposals are easier to compare. One quote may have a lower system price, another may have better equipment or workmanship coverage, and a third may offer financing that matches your cash-flow needs.
Solar Contractors can help you find professionals serving residential, commercial, agricultural, and government projects, so you can spend less time searching and more time evaluating clear options. A free consultation is a practical first step when you need help understanding what a proposal includes.
The best financing choice is the one that leaves you comfortable with the payment, confident in the installation team, and clear about who benefits from the system over time. Find a contractor, ask for transparent numbers, and let the project earn your confidence before it earns your signature.